

Correlations and Covariance
Correlations describe how fluctuations of two observables are related in a specified quantum state. If large outcomes of tend to occur with large outcomes of , their covariance is positive; if large outcomes of one tend to accompany small outcomes of the other, it is negative. Zero covariance means only that there is no linear correlation of this kind.
For a state , define centered observables
The standard real covariance of two self-adjoint observables is
The symmetrization is invisible for commuting observables. For noncommuting observables it is essential: an ordered product such as can be complex and is not automatically an ordinary joint-outcome moment.
The calculations below use bounded self-adjoint observables, including finite matrices, unless an unbounded quadratic-form treatment is stated explicitly. For the probability theory behind compatible outcomes, see Variance and Covariance. Time-dependent correlators and response are developed in Quantum Dynamics and Formulations, while spatial correlations are developed in Quantum Many-Body Theory and Statistical Mechanics.
Required background. Expectation Values supplies operator moments; Variance and Standard Deviation supplies centered observables and spread.
Helpful background. Commutators explains why ordering matters for noncommuting observables.
Paired fluctuations
Section titled “Paired fluctuations”For classical random variables with a joint distribution, covariance is
The sign is determined by paired deviations from the means. Outcomes in the same-sign quadrants contribute positively; outcomes in opposite-sign quadrants contribute negatively.
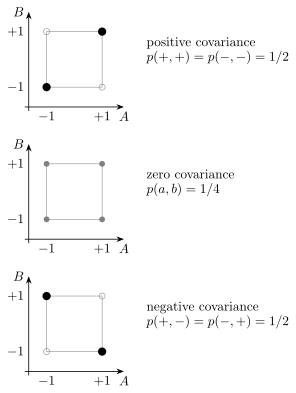
For centered binary outcomes , weight on the equal-sign pairs gives positive covariance, uniform weight gives zero covariance, and weight on the opposite-sign pairs gives negative covariance. These are ordinary joint distributions and therefore model compatible or separately localized measurements.
Covariance depends on the pairing. Knowing the separate marginal distributions of and is not enough to determine it.
Compatible observables and joint probabilities
Section titled “Compatible observables and joint probabilities”For finite-dimensional commuting observables,
their spectral projectors commute and define a joint projective measurement. If and are the spectral projectors, then
The projectors are mutually orthogonal, positive, and sum to the identity over all joint outcomes. The marginals are
The covariance is then the ordinary joint-distribution statistic
In infinite-dimensional settings, the precise compatibility condition is commutation of the spectral measures, often called strong commutativity. Formal commutators of unbounded operators require domain care and do not by themselves replace that spectral condition.
Symmetrized covariance
Section titled “Symmetrized covariance”Expanding the centered observables gives
Equivalently, using the anticommutator ,
The covariance is real and symmetric:
It reduces to variance on the diagonal:
The commutator and anticommutator split is developed algebraically at Commutators and Anticommutators. The Hermitian symmetric-product interpretation is developed in Anticommutators.
Ordered covariance and the commutator
Section titled “Ordered covariance and the commutator”The ordered centered product is
It decomposes as
For self-adjoint and , the covariance is real and is purely imaginary whenever the expressions are defined. Thus
The real part describes symmetrized fluctuation alignment. The imaginary part records noncommutativity. Neither statement creates a simultaneous sharp joint distribution for incompatible observables.
Quadratic-form definition
Section titled “Quadratic-form definition”For a pure state and possibly unbounded observables, a safer definition uses the centered vectors
If and both variances are finite, define
This requires the vectors and , but it does not automatically require or to exist. The anticommutator expression should be interpreted through this quadratic form when operator-product domains are problematic.
Correlation coefficient
Section titled “Correlation coefficient”When both standard deviations are nonzero, define
Cauchy–Schwarz gives
The coefficient is dimensionless and invariant under positive affine rescalings. Its sign reverses if exactly one observable is multiplied by a negative number.
For a pure state the relevant centered vectors are and . For a mixed state, use the Hilbert–Schmidt vectors and with inner product . The interpretations are then:
- means the centered operator-state vectors saturate Cauchy–Schwarz with positive proportionality.
- means they saturate it with negative proportionality.
- means zero symmetrized linear covariance.
Only when and admit a joint probability law do the first two cases reduce to the classical statement of a perfectly aligned or anti-aligned linear relation between random variables.
If either variance vanishes, is undefined rather than zero. In that case the corresponding observable has no fluctuations to normalize.
Zero covariance is not independence
Section titled “Zero covariance is not independence”Statistical independence implies factorization of every suitable product moment for a joint distribution, and hence zero covariance. The converse is false. A nonlinear dependence can have zero covariance.
In quantum mechanics, zero symmetrized covariance is even less restrictive:
- It does not imply that and commute.
- It does not imply a joint sharp probability distribution.
- It does not imply that two subsystems are in a product state.
- It does not rule out higher-order or nonlinear correlations.
For example, let a compatible outcome be uniform on and let . Then , so the covariance vanishes. Nevertheless, is completely determined by . Zero covariance misses this nonlinear dependence.
Covariance matrices
Section titled “Covariance matrices”For self-adjoint observables , define the real covariance matrix
It is real and symmetric. Its diagonal entries are variances:
For any real vector ,
Hence is positive semidefinite. Every principal minor is nonnegative, yielding
which is the bound behind .
Linear changes of observables
Section titled “Linear changes of observables”For real coefficients,
Constant shifts disappear after centering. For a vector of observables transformed by a real matrix ,
the covariance matrix transforms as
This rule is useful for changing quadratures, rotating spin components, or forming collective observables.
Recovering covariance from variances
Section titled “Recovering covariance from variances”Expanding the variance of a sum gives the polarization identity
Therefore
An equivalent symmetric form is
These identities remain valid for noncommuting observables because variance of automatically contains the symmetrized cross term. They also suggest an operational route: estimate variances of the separately implemented observables and , rather than claiming a simultaneous sharp measurement of and .
Connected correlations
Section titled “Connected correlations”The ordered connected two-point function is
For commuting observables this equals their covariance. For noncommuting observables it is order dependent and may be complex:
One must state whether a problem uses , , a symmetrized correlator, a time-ordered correlator, or a retarded commutator. These objects answer different physical questions.
Connected Correlation Functions explains cumulants, cluster decomposition, spatial decay, and the many-body meaning of connectedness. For time- and position-dependent applications, see Correlation Functions Overview.
Local observables on two subsystems
Section titled “Local observables on two subsystems”For a bipartite system, local observables
commute. Their product is
so the local covariance is
For a product state , all such local product expectations factorize, so every local covariance vanishes. A separable mixture can nevertheless have nonzero local covariance because the classical mixing variable correlates the subsystems.
The full relation among marginals, classical correlations, and entanglement is developed at Marginals and Correlations.
Example: Bell-state correlations
Section titled “Example: Bell-state correlations”Consider
For
the local means vanish,
while
Thus
The local outcomes are individually random and perfectly correlated.
Correlation alone does not certify entanglement
Section titled “Correlation alone does not certify entanglement”The separable mixed state
has the same statistics:
Therefore its covariance is also one. The Bell state and this separable state differ in other measurement bases and in their coherence, but one covariance cannot distinguish them. See Classical Correlation versus Entanglement for methods that distinguish the two.
Example: noncommuting Pauli observables
Section titled “Example: noncommuting Pauli observables”Take and let
The means vanish, and the anticommutator is zero:
Hence
But
The zero real covariance does not imply compatibility. The imaginary ordered part records
Example: position–momentum covariance
Section titled “Example: position–momentum covariance”For one-dimensional position and momentum,
It measures the linear tilt of phase-space fluctuations. Consider the chirped Gaussian
Its moments are
The covariance vanishes for an unchirped packet and changes sign with . The determinant obeys
so this pure Gaussian saturates the Schrödinger uncertainty relation.
Covariance and uncertainty
Section titled “Covariance and uncertainty”For a pure state, Cauchy–Schwarz applied to and gives the Schrödinger–Robertson inequality
For unbounded observables on , use in place of the commutator term unless both operator products are defined. The covariance term is the real part of the centered overlap, and the commutator term is its imaginary part. Dropping the nonnegative covariance term gives the weaker Robertson bound. The derivation and equality conditions are at General Uncertainty Relations.
Common pitfalls
Section titled “Common pitfalls”State the ordering. A symmetrized covariance is real; an ordered connected product can be complex. They coincide for compatible observables but generally answer different questions otherwise.
Correlation does not by itself establish entanglement. A mixture of product states can have perfectly correlated outcomes in a chosen basis. Compare additional measurements or apply a suitable entanglement criterion.
Do not divide by zero spread. The correlation coefficient is undefined if either standard deviation vanishes. Covariance remains defined and is zero in that case.
Exercises
Section titled “Exercises”1. Covariance with itself
Section titled “1. Covariance with itself”Show directly from the symmetrized definition that
Solution
Setting gives
2. A binary joint distribution
Section titled “2. A binary joint distribution”Two commuting observables have outcomes with
and
where . Find the means, variances, covariance, and correlation coefficient.
Solution
Each marginal is uniform, so
The product is for equal signs and for opposite signs. Hence
Because the means vanish,
3. Bell-state covariance
Section titled “3. Bell-state covariance”For , calculate the covariance and correlation coefficient of and .
Solution
Each local outcome is with equal probability, so
The outcomes always have equal signs, and
Therefore
4. Correlation without entanglement
Section titled “4. Correlation without entanglement”For
compute the same covariance as in Exercise 3. Why does the result not certify entanglement?
Solution
The local means vanish and every preparation gives equal signs, so
and the covariance is . But is explicitly a convex mixture of the product states and . It is separable. The covariance detects correlation in this measurement basis, not the source of that correlation.
5. Noncommuting Pauli pair
Section titled “5. Noncommuting Pauli pair”In the state , evaluate
its real covariance, and its commutator contribution.
Solution
Both means vanish, so the centered operators equal the original operators. Using ,
The real part is zero:
The commutator contribution is
6. Polarization from variances
Section titled “6. Polarization from variances”Prove that
without assuming that and commute.
Solution
Centering is linear:
Therefore
Subtracting the second equation from the first gives the result. The cross terms enter as , so no commutativity assumption is needed.
7. Positivity of a two-observable covariance matrix
Section titled “7. Positivity of a two-observable covariance matrix”Let
Use positivity to derive when both variances are nonzero.
Solution
For real ,
Thus is positive semidefinite, so its determinant is nonnegative:
Dividing by the positive product of variances gives
8. Chirped Gaussian uncertainty determinant
Section titled “8. Chirped Gaussian uncertainty determinant”Suppose a state has
and
Evaluate the covariance-corrected uncertainty determinant.
Solution
Substitution gives
Therefore
The chirp increases both momentum variance and position–momentum covariance in exactly the combination needed to preserve saturation of the Schrödinger uncertainty relation.
References
Section titled “References”- L. E. Ballentine, Quantum Mechanics: A Modern Development, 2nd ed., World Scientific, 2014, Chapters 2–3.
- M. A. Nielsen and I. L. Chuang, Quantum Computation and Quantum Information, 10th anniversary ed., Cambridge University Press, 2010, Chapters 2 and 12.
- H. P. Robertson, “The Uncertainty Principle,” Physical Review 34, 163–164 (1929).
- J. J. Sakurai and J. Napolitano, Modern Quantum Mechanics, 3rd ed., Cambridge University Press, 2020, Chapters 1–2.
- E. Schrödinger, “Zum Heisenbergschen Unschärfeprinzip,” Sitzungsberichte der Preussischen Akademie der Wissenschaften, Physikalisch-mathematische Klasse, 296–303 (1930).
- R. Shankar, Principles of Quantum Mechanics, 2nd ed., Springer, 1994, Chapters 1 and 4.
- J. von Neumann, Mathematical Foundations of Quantum Mechanics, Princeton University Press, 1955, Chapters II–III.