

Connected Correlation Functions
A connected correlation function removes every contribution that factorizes into lower-order expectation values. At second order and in a fixed operator order,
Equivalently, with centered operators
one has
The subtraction isolates joint fluctuations not explained by the one-point profiles. Spatially, it is the object that clusters in a pure short-range-correlated phase. Combinatorially, its higher-order generalizations are cumulants. Diagrammatically, connected pieces are selected by the logarithm of a generating functional.
Connected does not mean symmetrized, entangled, interacting, irreducible, amputated, or causal. Each of those words performs a different operation.
Helpful background. Equal-Time Correlations introduces spin, density, and coherence channels; Correlations and Covariance explains why ordered and symmetrized products differ.
Connected moments preserve operator order
Section titled “Connected moments preserve operator order”We use and assume the moments exist. The first formulas below use ordinary cumulants of commuting variables or ordered bosonic observables. Bare fermionic fields instead require graded cumulants with the corresponding permutation signs. A finite lattice has sites and linear size ; separation means distance between operator supports.
Subtracting lower moments does not permit reordering operators. In particular, and can differ.
Two-Point Connected Function
Section titled “Two-Point Connected Function”For insertions labeled by position, time, component, or mode,
The disconnected product is what this particular second moment would contain if the two insertions factorized:
Thus
This is an algebraic identity, not an approximation.
Complex ordered values
Section titled “Complex ordered values”For Hermitian and ,
An ordered connected correlator may be complex. Its symmetrized real part is
Connected subtraction changes means; symmetrization changes order. Correlations and Covariance explains the latter as a measurement statistic.
Higher Connected Functions
Section titled “Higher Connected Functions”For the ordinary cumulant convention, at third order,
The operator order inside each moment is inherited from the declared prescription. For example, retains before .
If every one-point function vanishes, the fourth connected function is
For nonzero means, additional partitions containing singleton blocks must be included.
General partition formula
Section titled “General partition formula”Let be the set of partitions of . For a specified source and ordering convention,
The inner product follows the inherited order within the block. The outer factors are ordinary complex numbers and commute. For fermionic fields, contour-ordered objects, or generalized operator exponentials, signs and source types must follow the chosen generating convention rather than being guessed from the classical formula.
Generating Connected Cumulants
Section titled “Generating Connected Cumulants”For commuting scalar sources and a declared ordered exponential, define
where denotes the ordering prescription. Normalize so that
The cumulant-generating functional is
Then
with the ordering and any convention-dependent factors fixed by the definition of .
The logarithm removes products of independent pieces because
for factorized sectors, while
Mixed derivatives between independent sectors therefore vanish.
Connected is not the same as one-particle irreducible. A connected function may still separate after cutting one internal line. Legendre transformation, amputation, and one-particle irreducibility are later operations.
Gaussian States and Wick Factorization
Section titled “Gaussian States and Wick Factorization”For observables linear in the canonical fields of a Gaussian state, with a specified ordering prescription, all connected cumulants above second order vanish:
At fourth order with zero means,
for commuting Gaussian variables or bosonic fields in a compatible ordering. Fermionic Wick contractions carry permutation signs. Substituting the Wick sum into the fourth-cumulant formula gives zero.
The restriction to linear fields matters: nonlinear observables such as a squared Gaussian field generally have nonzero higher cumulants. Conversely, vanishing of one measured fourth cumulant does not prove that a state is Gaussian. When the generating function exists near zero, a quadratic logarithm characterizes Gaussianity; one selected moment does not establish that property.
Interactions often generate non-Gaussian connected cumulants, but “interacting” and “non-Gaussian” are not synonyms. Quadratic effective theories can describe interacting systems approximately, while a noninteracting Hamiltonian with a non-Gaussian initial state can have nonzero higher cumulants.
Connected Is Not Entangled
Section titled “Connected Is Not Entangled”If two regions are in a product state,
then for every local pair and ,
The converse is false for one selected pair. A state can be correlated in operators not tested by and .
Even a nonzero connected correlator does not prove entanglement. Consider
This state is separable, yet
The connected correlation is classical uncertainty about which aligned product state was prepared.
If factorization holds for complete operator bases on both regions,
for all , then the joint state is a product. That is a complete tomography statement, much stronger than checking one correlator. Marginals and Correlations derives the reconstruction statement.
Connected Is Not Interaction
Section titled “Connected Is Not Interaction”Connected correlations can arise without dynamical interactions:
- exchange statistics produces density antibunching or bunching;
- a fixed total charge produces compensating anticorrelation;
- a classically correlated mixture has nonzero connected moments;
- an initially entangled state can evolve under a noninteracting Hamiltonian;
- common external randomness can correlate otherwise uncoupled sectors.
Conversely, an interacting Hamiltonian does not guarantee a nonzero selected correlator. Symmetry can force it to vanish, a product mean-field approximation can set it to zero by construction, or the chosen operators can miss the correlated channel.
Connected correlation diagnoses failure of moment factorization for specified operators and a specified state. Distinguishing these origins requires more information about the state and preparation.
Spatial Cluster Decomposition
Section titled “Spatial Cluster Decomposition”Let and be bounded local operators supported in regions and . A state clusters for this operator class if
as
Cluster decomposition says that sufficiently distant bounded experiments become independent at the level of local moments. It is a property of the state, the operator class, and the limiting procedure. It is not guaranteed by writing down a local Hamiltonian.
Pure phases and mixtures
Section titled “Pure phases and mixtures”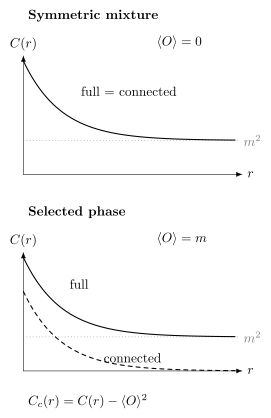
Phase selection changes what the subtraction removes. In a symmetric mixture, , so the connected correlator equals the full correlator and can retain the order plateau. In a selected pure phase, the full correlator approaches while subtraction leaves a connected fluctuation that clusters to zero.
Here a pure phase means an extremal thermodynamic equilibrium phase, not necessarily a pure density operator: a finite-temperature pure phase is usually mixed quantum mechanically. Suppose a broken-symmetry pure phase has
Cluster decomposition gives
while
Now form an equal mixture of two phases with order parameters . The mixture has
but can retain
Therefore
The mixture fails cluster decomposition because a global classical label, the selected phase, remains correlated across arbitrary distance.
A finite symmetry-preserving ground state can behave similarly over distances below the system size. It is incorrect to infer absence of order from a zero one-point function or to infer absence of a pure clustering phase from the finite-volume connected plateau. Spontaneous Symmetry Breaking explains cat states, symmetry-breaking sources, and thermodynamic phase selection.
Exponential Clustering
Section titled “Exponential Clustering”A short-range-correlated phase often satisfies
at large separation, possibly with an algebraic prefactor.
For finite-range quantum spin systems with bounded local terms, a unique ground state and a uniform gap above it imply exponential clustering of bounded local observables. A gap that closes as the volume grows is insufficient. The theorem’s correlation-length bound is controlled parametrically by a locality velocity divided by the gap, but it is not generally an equality for the physical correlation length. Area Laws separates this clustering theorem from the stronger entropy statement and records where the converse is rigorous.
Important qualifications include:
- ground-state degeneracy and phase-sector selection;
- operators that connect different ground sectors;
- long-range interactions;
- unbounded local degrees of freedom;
- gauge constraints and nonlocal observables;
- finite temperature and thermal phase transitions;
- topological sectors and boundary modes.
A spectral gap is a powerful sufficient ingredient in the local setting, not a universal one-line equivalence between “gapped” and “exponential” for every operator and geometry.
Correlation Lengths
Section titled “Correlation Lengths”There are several useful but inequivalent correlation lengths.
Asymptotic exponential length
Section titled “Asymptotic exponential length”For
is the exponential decay length. The amplitude, power , oscillation wavevector , and phase must be handled before fitting.
Several transfer-matrix eigenvalues or excitation channels can produce several lengths:
The largest dominates only if its amplitude is nonzero in the chosen operator channel and the asymptotic regime is reached.
Effective local length
Section titled “Effective local length”For a positive, nonoscillatory pure exponential sampled with spacing ,
A plateau of can identify an asymptotic window. Sign changes, noise near zero, algebraic prefactors, multiple exponentials, and boundaries can make this estimator unstable or biased.
Second-moment length
Section titled “Second-moment length”For a periodic lattice and an ordering wavevector , a common finite-size estimator is
in lattice-spacing units. Here is the Fourier transform of the connected correlator and is the smallest compatible momentum increment.
This formula assumes a suitable Ornstein–Zernike-like small-momentum shape and geometry. Landau–Ginzburg Theory Preview derives the Gaussian kernel and its pole length; the estimator here remains an operational definition rather than an assumption that the full system is Gaussian. Other boundary conditions, anisotropic systems, conserved constraints, and tensor channels require modified estimators. The second-moment length need not equal the asymptotic exponential length away from a scaling regime.
Structure Factors develops the Fourier normalization; the formula appears here only to distinguish common definitions of .
Algebraic and Critical Correlations
Section titled “Algebraic and Critical Correlations”At a scale-invariant point or in a stable critical phase,
where is the scaling dimension of the operator channel.
There is no finite exponential correlation length at the critical point. Away from it, a scaling form is
with
Here measures distance from criticality and the branches can differ on the two sides.
Critical behavior requires several cautions:
- different operators have different scaling dimensions;
- symmetry can suppress the leading channel;
- dangerously irrelevant variables can modify naive finite-size scaling;
- logarithmic corrections can imitate drifting powers;
- anisotropic systems can have direction-dependent lengths;
- a quantum critical point includes temporal scaling and a dynamical exponent;
- a finite range of sizes can fit both a large finite and a power law.
Gaplessness does not force every correlator to decay algebraically, and one algebraic correlator does not determine the entire universality class.
Critical Exponents and Scaling explains the anomalous dimension, Fisher relation, finite-size corrections, and dynamic scaling.
Order and fluctuations ask different questions
Section titled “Order and fluctuations ask different questions”Use the full long-distance correlator or a squared order parameter to test whether a phase has order. Use the connected function to study fluctuations around a selected phase. In a symmetric finite state or mixture, the means can vanish, leaving the order plateau inside the connected function. Long-Range Order develops the corresponding finite-size tests.
A fixed-number example: small tails with a finite sum
Section titled “A fixed-number example: small tails with a finite sum”Consider a uniform classical mixture of all binary occupation strings with exactly occupied sites among . Write . Counting configurations gives
Therefore
Each offsite value tends to zero at fixed filling as , but their sum stays and exactly cancels the onsite variance. For , , the diagonal entries are and the twelve off-diagonal entries are . Every row sums to zero, as required by .
This example concerns the constraint-induced tail. In an interacting state, short-distance connected correlations generally remain nonzero as ; only the additional background vanishes pointwise. Local ensemble equivalence therefore need not imply identical integrated zero-momentum fluctuations.
Extensive Observables and Cumulant Scaling
Section titled “Extensive Observables and Cumulant Scaling”For an extensive observable
its variance is the sum of connected two-point functions:
More generally,
If the connected -point function is absolutely summable in all relative coordinates, only tuples within a finite correlation volume contribute appreciably to each anchor point. Then
for a sequence with a uniform summability bound. Proportionality with a nonzero coefficient needs an additional assumption: a fixed total charge, for example, can have exactly zero variance.
Near criticality or with long-range order, the correlation volume grows and cumulants can scale superextensively. Ratios such as Binder cumulants exploit this scaling, but their normalization and universal limits depend on geometry, boundary conditions, order-parameter symmetry, and ensemble.
The fluctuation and susceptibility consequences are developed in Fluctuations and Susceptibilities.
Inhomogeneous Profiles and Averaging Order
Section titled “Inhomogeneous Profiles and Averaging Order”For an open, trapped, or disordered system, define the displacement-averaged connected correlator by subtracting local means before averaging:
This generally differs from
The difference is the spatial covariance of the one-point profiles. Subtracting global means can mistake a trap shape, domain wall, density gradient, or disorder pattern for correlated fluctuations.
If disorder averaging is also performed, distinguish:
from
The second includes sample-to-sample covariance of the means. Both can be useful, but they answer different questions.
Dynamic Connected Functions
Section titled “Dynamic Connected Functions”For a stationary state,
The disconnected term contributes
to the ordinary spectrum. Subtracting it removes that particular elastic line.
It does not remove zero-frequency weight from conserved projections, degenerate transitions, phase mixtures, or integrability. A dynamical connected plateau must be interpreted with the same state and limit care as a spatial one.
For nonstationary states,
Time-Dependent Correlations develops the two-time and spectral analysis.
Linked-Cluster and Diagrammatic Meaning
Section titled “Linked-Cluster and Diagrammatic Meaning”In a perturbative expansion, disconnected vacuum or insertion clusters can scale with volume and proliferate combinatorially. Normalizing the generating functional removes vacuum-only factors, while taking its logarithm selects connected insertion structures.
This gives the linked-cluster principle:
is extensive when connected clusters are local and summable, even though itself grows exponentially with volume.
Connected diagrams can still contain self-energy insertions, articulation lines, or reducible subgraphs. “Connected,” “one-particle irreducible,” “skeleton,” and “amputated” identify different graph operations. Diagrammatic Methods Preview explains those graph operations.
Measurement and Estimation
Section titled “Measurement and Estimation”Suppose independent, identically distributed preparations yield real scalar outcomes and . The unbiased sample covariance is
Using after estimating both means from the same finite sample gives the maximum-likelihood estimator for some models but has expectation times the covariance for independent identically distributed samples. It is biased toward zero, including when the true covariance is negative.
For quantum observables that do not commute, one experimental record does not provide an ordinary joint sample without a specified sequential, weak, or ancilla-assisted protocol. The estimator must match the ordered, symmetrized, or response object actually measured.
Further cautions:
- spatial pairs within one image are not statistically independent;
- Markov-chain samples have an autocorrelation time;
- estimating and subtracting large means amplifies relative error;
- detector drift can create common-mode connected signals;
- postselection induces correlations;
- uncertainty in local means must be propagated into ;
- fitting requires covariance among separations.
Numerical Evaluation
Section titled “Numerical Evaluation”Exact diagonalization
Section titled “Exact diagonalization”Evaluate the full moment and one-point functions in the same state and convention. Exact identities from symmetry, fixed charges, and onsite algebra provide checks. Do not round the separate terms before subtraction.
Tensor networks
Section titled “Tensor networks”For matrix-product states, transfer-matrix eigenvalues determine asymptotic connected correlations. For an injective translation-invariant MPS, a unique leading transfer eigenvalue generates the disconnected product; subleading eigenvalues generate decay lengths. Multiple unit-modulus eigenvalues can retain nondecaying correlations, as in cat states. Finite bond dimension can impose an artificial finite correlation length at criticality.
Quantum Monte Carlo
Section titled “Quantum Monte Carlo”Connected estimators can be formed directly from centered configurations or by subtracting ensemble means. Improved estimators may reduce variance. Near criticality, long autocorrelation times and covariance across distances must enter the error analysis.
Generating functions
Section titled “Generating functions”Higher cumulants can be obtained from derivatives of , but numerical differentiation amplifies noise. Automatic differentiation, reweighting, or direct cumulant estimators should be checked against low-order moment formulas and exact symmetries.
Common pitfalls
Section titled “Common pitfalls”One zero correlator does not establish a product state. Complete local operator bases are needed for that conclusion; one nonzero correlator, conversely, can be entirely classical.
A symmetric mixture need not cluster. The shared phase label can persist across arbitrary distance. State how a phase is selected before interpreting its connected tail.
One fitted length need not describe every channel. Oscillations, power-law prefactors, finite bond dimension, and boundaries can all distort a two-point ratio. Compare fit windows and sizes before assigning an asymptotic correlation length.
Exercises
Section titled “Exercises”Exercise 1: Centered-operator identity
Section titled “Exercise 1: Centered-operator identity”Show that
without assuming that and commute.
Solution
Expand in the written order:
The last three terms combine to one subtraction:
Only scalar means were moved; the operators themselves were never reordered.
Exercise 2: Third cumulant of centered operators
Section titled “Exercise 2: Third cumulant of centered operators”Prove that
for the fixed order .
Solution
Expand
without changing the order. Taking the expectation gives
The final four scalar terms sum to
reproducing the third-cumulant formula.
Exercise 3: Classical correlation without entanglement
Section titled “Exercise 3: Classical correlation without entanglement”For
compute , , and . Explain why the result does not prove entanglement.
Solution
With and ,
and similarly . Both components have aligned outcomes, so
Therefore
The density operator is explicitly a convex mixture of product states. It is separable, and the correlation records the classical shared label versus .
Exercise 4: Fixed-number anticorrelation
Section titled “Exercise 4: Fixed-number anticorrelation”Let be sharp. Prove
What does this imply if the onsite variance is positive?
Solution
Sharp total number means
on the support of the state. Thus
The term is . If it is positive, the sum of offsite connected terms must be negative. This compensation follows from conditioning on total number.
Exercise 5: Gaussian fourth cumulant
Section titled “Exercise 5: Gaussian fourth cumulant”Assume zero one-point functions and Wick factorization
Show that .
Solution
For zero means,
Substituting the Wick sum cancels each pairing exactly, leaving zero. For fermionic operators the same conclusion holds when both the Wick expansion and cumulant convention use the same ordering and permutation signs.
Exercise 6: Pure phase versus symmetric mixture
Section titled “Exercise 6: Pure phase versus symmetric mixture”Suppose two pure phases have
and each clusters:
Compute the long-distance connected correlator in either pure phase and in their equal mixture.
Solution
In a pure phase,
In the equal mixture, the one-point function cancels:
The two-point function does not cancel:
Hence
The mixture fails clustering because the global phase label remains shared at arbitrary distance.
Exercise 7: Variance of an extensive sum
Section titled “Exercise 7: Variance of an extensive sum”For
show
Why does rapid clustering usually make this extensive?
Solution
Expand
If the connected function is summable, then for each anchor only a finite correlation volume of contributes appreciably. The inner sum approaches a size-independent constant away from boundaries, while the number of anchors is proportional to . Thus . If the limiting inner sum is nonzero, the variance is proportional to ; conservation constraints can instead make it vanish.
Exercise 8: Effective correlation length
Section titled “Exercise 8: Effective correlation length”Suppose
is sampled at and . Show that
Name two reasons this estimator can fail on real data.
Solution
The ratio is
Taking the logarithm gives
which yields the stated formula.
The estimator can fail or drift because of oscillatory sign changes, algebraic prefactors, multiple exponentials, statistical noise near zero, boundary effects, or using distances outside the asymptotic regime.
Further connections
Section titled “Further connections”- Mutual Information in Many-Body Systems bounds total correlation using connected observables.
- Matrix Product States relates transfer eigenvalues to spatial decay.
- Sources and Generating Functionals develops source differentiation.
- Structure Factors gives the Fourier normalizations used for correlation-length estimates.
- Finite-Size Scaling in Numerics explains extrapolation and its limitations.
References
Section titled “References”- J. Cardy, Scaling and Renormalization in Statistical Physics, Cambridge University Press (1996).
- P. Coleman, Introduction to Many-Body Physics, Cambridge University Press (2015).
- A. L. Fetter and J. D. Walecka, Quantum Theory of Many-Particle Systems, Dover (2003).
- N. Goldenfeld, Lectures on Phase Transitions and the Renormalization Group, Addison-Wesley (1992).
- M. B. Hastings and T. Koma, “Spectral Gap and Exponential Decay of Correlations”, Communications in Mathematical Physics 265, 781–804 (2006).
- R. Kubo, “Generalized Cumulant Expansion Method”, Journal of the Physical Society of Japan 17, 1100–1120 (1962).
- B. Nachtergaele and R. Sims, “Lieb–Robinson Bounds and the Exponential Clustering Theorem”, Communications in Mathematical Physics 265, 119–130 (2006).
- B. Nachtergaele, Y. Ogata, and R. Sims, “Propagation of Correlations in Quantum Lattice Systems”, Journal of Statistical Physics 124, 1–13 (2006).
- J. W. Negele and H. Orland, Quantum Many-Particle Systems, Westview Press (1998).
- S. Sachdev, Quantum Phase Transitions, 2nd ed., Cambridge University Press (2011).